
There's no secret cheap flood carrier in Louisiana. NFIP flood premiums are set federally under Risk Rating 2.0, so shopping company to company doesn't cut the price the way it does for auto insurance. “Cheapest” really means the levers that lower your specific premium: a higher deductible, the right coverage amount, elevation and mitigation, and your community's Community Rating System discount — which can reduce NFIP premiums 5%–45%. The goal is the lowest honest rate for your home, not a stripped-down policy.
If you're searching for the cheapest flood insurance in Louisiana, here's the honest truth up front: there's no secret cheap carrier to find. NFIP flood premiums are set federally, so shopping company to company doesn't cut your price the way it does for auto insurance. What actually lowers your cost is a set of specific levers on your own policy and property — your deductible, coverage choices, mitigation, and community discounts. This guide walks through each one, and what a “cheap” flood policy can quietly leave out. The team at The Root Agency in Livingston writes NFIP coverage and can find your lowest honest rate.
Key takeaways
- NFIP flood rates are federally set, so carrier-shopping doesn't lower the price like it does for auto.
- The real levers: a higher deductible, right-sized coverage, elevation, and mitigation.
- Community Rating System discounts can cut NFIP premiums 5%–45% in participating Louisiana communities.
- A “cheap” policy that skips contents coverage or under-insures the building leaves you exposed.
- “Cheapest” should mean the lowest honest rate for your home — not the least coverage.
Why does flood insurance pricing work differently from auto or home?
Because the rates are federal, not competitive. With auto or home insurance, different carriers price the same driver or house differently, so shopping around genuinely lowers your cost. NFIP flood insurance doesn't work that way — the premium is set by FEMA's federal rating system, so the same NFIP coverage on the same home costs the same regardless of which agent writes it.
That changes the whole strategy. You can't out-shop an NFIP premium the way you can an auto quote, so “finding the cheapest” isn't about carriers — it's about the factors FEMA uses to price your specific property. Once you understand that, you stop hunting for a magic low quote and start pulling the levers that actually move your rate.
What actually lowers your flood premium?
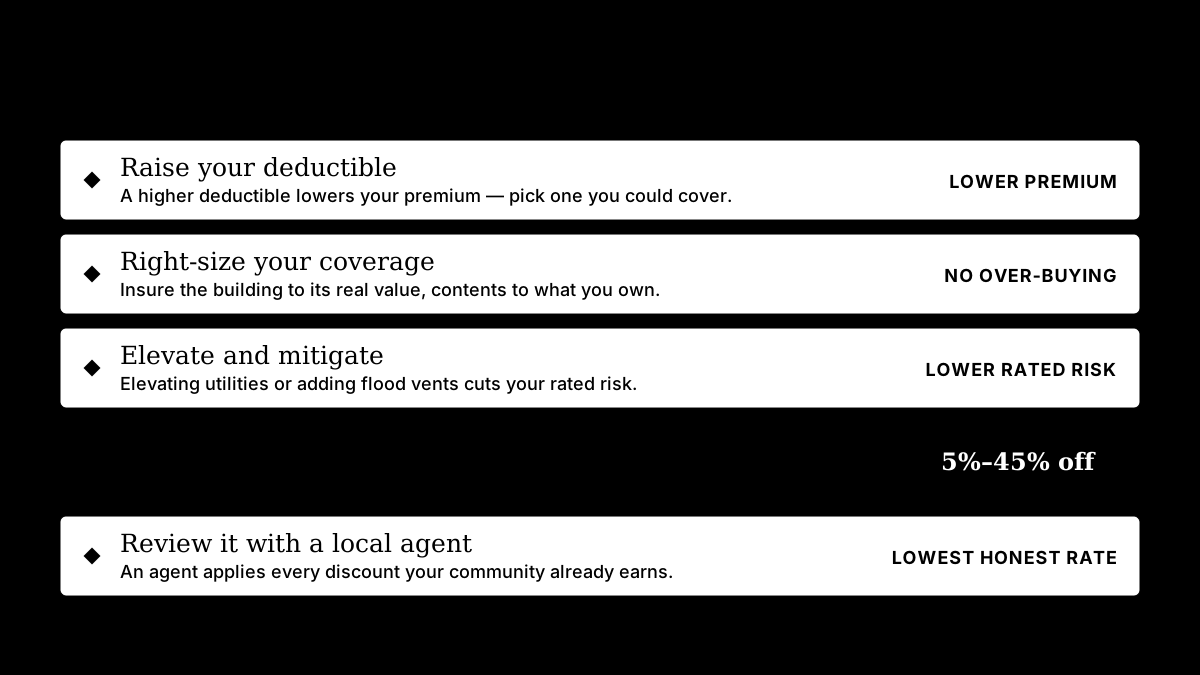
The factors tied to your property and your coverage choices. According to FloodSmart, these are the genuine ways to reduce an NFIP premium:
- Raise your deductible. A higher deductible lowers your premium — choose an amount you could cover after a loss.
- Right-size your coverage. Insure the building to its real value and contents to what you actually own, rather than over-buying.
- Elevate and mitigate. Elevating the structure or your utilities, and adding flood vents, can reduce your rated risk under Risk Rating 2.0.
- Benefit from your community's discount. Many Louisiana parishes participate in FEMA's Community Rating System, which discounts NFIP premiums 5%–45% community-wide — applied whether or not you're in a high-risk zone.
Those are the real levers. Notice that none of them involve switching carriers to chase a lower NFIP number — because that number is fixed. They involve lowering your risk or adjusting your coverage.
NFIP vs. private on cost — and the catch
Private flood insurance can sometimes come in cheaper than NFIP for certain lower-risk Louisiana homes — but there's a catch worth understanding before you chase the lower number. Private policies use their own underwriting, so a private quote can undercut NFIP for some homes and cost more for others; it varies.
The catch is what you might give up. NFIP has continuous-coverage protections and federal stability, and switching to a private policy purely for a lower premium can risk those protections — sometimes in ways that cost more later than the savings were worth. So “cheaper today” isn't always “cheaper over the life of your home.” If you're weighing the two, our guide to private vs. NFIP flood insurance in Louisiana context and an agent's review help you compare honestly rather than just by sticker price.
What can a “cheap” flood policy quietly leave out?
The coverage you'll actually need. The easiest way to make any flood policy “cheap” is to leave things out — and that's exactly where homeowners get hurt after a flood.
Watch for three quiet gaps:
- No contents coverage. Building-only policies are cheaper, but they don't pay for your belongings — furniture, electronics, appliances that aren't built in. In a Louisiana flood, that's often most of your loss.
- Under-insured building coverage. Buying less building coverage than your rebuild cost lowers the premium but leaves a gap in a total loss.
- A deductible you can't actually afford. A high deductible cuts the premium, but only helps if you could pay it when water's in your home.
A policy that's cheap because it's efficient is smart; a policy that's cheap because it's hollow is a future bill. The goal is the lowest price for coverage that still makes you whole.
How do you get your lowest honest rate?
Work the real levers, then let a local agent confirm the number. Since you can't shop the NFIP rate itself, your lowest honest rate comes from optimizing what you control: an appropriate deductible, right-sized building and contents coverage, any mitigation you've done, and your community's CRS discount.
A local agent who writes NFIP coverage can pull your property's rate, apply every discount your community earns, and show you where mitigation would lower it further — then quote the coverage you actually need at the best available price. That's the honest version of “cheapest”: not the least coverage you can buy, but the lowest price for coverage that protects your home. For the broader picture on Louisiana costs, see why insurance is so expensive in Louisiana.
Want your lowest honest flood rate?
Since you can't shop the NFIP rate away, the savings come from working the levers you control — and knowing which ones apply to your home. The team at The Root Agency writes NFIP flood coverage and can apply every discount your community earns while keeping the protection you actually need. When you're ready, start on our flood insurance page or contact your Livingston-area team, and we'll find your lowest honest rate.
This article is general information, not a quote or insurance advice. Flood premiums depend on your specific property — talk with a licensed agent about your coverage.