
A hurricane deductible in Louisiana is a separate, percentage-based deductible — commonly 2%–5% of your dwelling coverage — that applies only when a named storm causes the damage. Because it's a percentage of your home's insured value rather than a flat dollar amount, your out-of-pocket cost is far higher than your standard deductible. On a home with $300,000 in dwelling coverage, a 2% hurricane deductible is $6,000 before coverage begins. Most homeowners don't realize this until they file a claim.
Your Louisiana hurricane deductible is usually a percentage of your home's insured value, not a flat dollar amount — which means a single named storm can cost you thousands out of pocket before your coverage pays a cent. Most homeowners never notice this line on their policy until they file a claim, and by then it's a shock. This guide explains exactly what a hurricane deductible is, how the percentage is calculated, what triggers it, why your standard deductible doesn't apply, and how to plan for the cost. Knowing your number before the storm is the entire point. The team at The Root Agency in Baton Rouge makes sure homeowners understand what they'd actually owe.
Key takeaways
- A hurricane deductible is separate from your standard deductible and applies only to named-storm damage.
- It's a percentage of your dwelling coverage (Coverage A) — commonly 2%–5% in Louisiana — not a flat dollar amount.
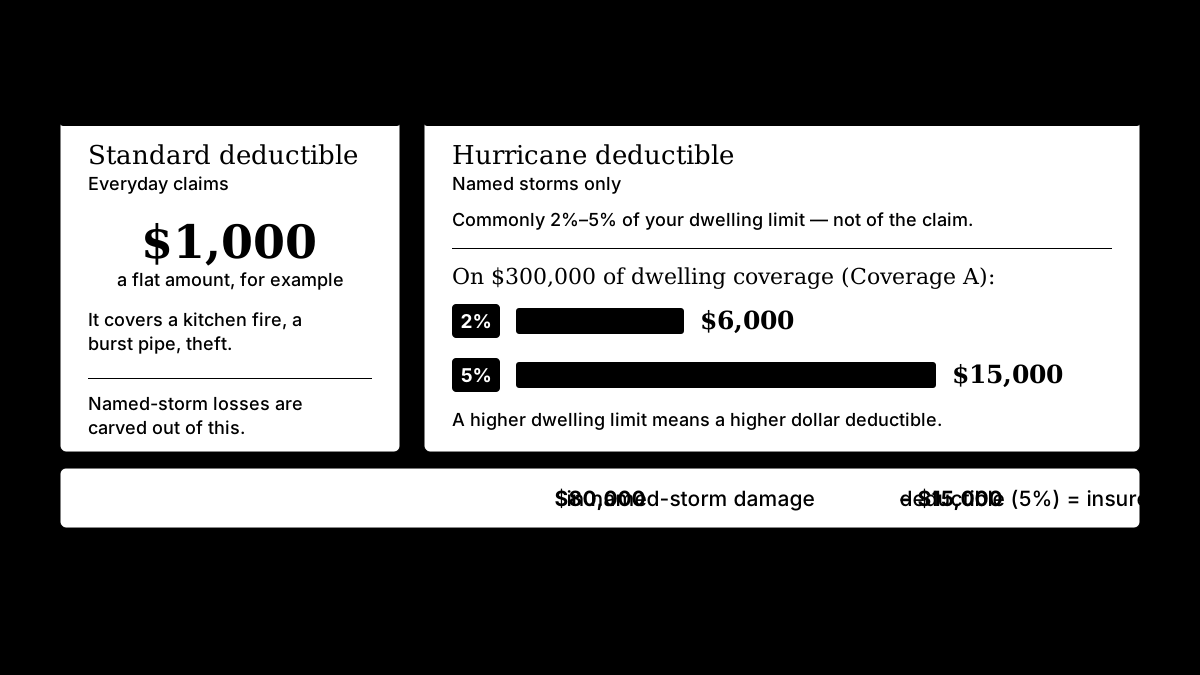
- On $300,000 of dwelling coverage, a 2% deductible is $6,000 out of pocket; a 5% deductible is $15,000.
- Under Louisiana law, the named-storm deductible generally applies once per calendar year, not per storm.
- Flood damage from a hurricane falls under separate flood insurance — not your hurricane deductible.
What is a hurricane deductible in Louisiana?
It's a separate deductible that applies only to damage from a named storm. Unlike your standard “all other perils” deductible, a hurricane deductible kicks in specifically when a hurricane or named storm causes the loss — and it's almost always calculated as a percentage of your dwelling coverage.
According to the Louisiana Department of Insurance, these percentage deductibles commonly run 2%–5% of your dwelling coverage limit, though they can be higher in the most coastal areas. That percentage structure is what makes them so much larger than a flat deductible — and why understanding yours before hurricane season matters so much in Louisiana.
How is the percentage deductible actually calculated?
It's a percentage of your Coverage A dwelling limit, not of the claim. That's the detail that catches people off guard, so it's worth walking through with real numbers.
Say your home is insured for $300,000 in dwelling coverage:
- A 2% hurricane deductible = $300,000 × 0.02 = $6,000 out of pocket.
- A 5% hurricane deductible = $300,000 × 0.05 = $15,000 out of pocket.
So if that home suffers $80,000 in named-storm damage with a 5% deductible, the insurer subtracts $15,000 and pays $65,000. The deductible is based on your home's insured value, which is why a higher dwelling limit also means a higher dollar deductible at the same percentage. Always check your policy's declarations page for your exact percentage — it's the number that determines your real exposure.
What triggers it — named storm, wind, or flood?
The trigger is a named or declared storm — not just any bad weather. Your hurricane deductible applies when the damage comes from a storm that's been named (or meets your policy's specific “named storm” trigger language), which is different from an ordinary thunderstorm.
Three distinctions matter:
- Named storm / hurricane → your percentage hurricane deductible applies.
- Ordinary wind or hail (not from a named storm) → your separate wind/hail deductible or standard deductible may apply instead.
- Flood → not covered by your homeowners policy at all, and not subject to this deductible.
That last point is critical in Louisiana: a hurricane often brings both wind and flooding, and the two are handled completely differently. Wind damage runs through your homeowners policy and its hurricane deductible; flood damage runs through separate flood insurance. See our guide on what triggers insurance coverage in Louisiana for how these distinctions play out.
Why doesn't your standard deductible apply?
Because Louisiana policies use a separate deductible specifically for catastrophic storm risk. Your standard deductible (a flat amount like $1,000) applies to everyday claims — a kitchen fire, a burst pipe, theft — but named-storm losses are carved out under the percentage hurricane deductible instead.
Insurers structure it this way because hurricanes produce enormous, clustered losses, and the percentage deductible shares more of that catastrophic risk with the homeowner. One consumer-friendly detail worth knowing: under Louisiana law, for policies issued or renewed since 2010, the named-storm deductible generally applies once per calendar year rather than resetting for every storm — so if multiple named storms hit in one year, you don't pay the full hurricane deductible each time. Confirm how your specific policy applies it, since terms vary.
How do you plan for the out-of-pocket cost?
Know your number now and set it aside. The worst time to learn your hurricane deductible is standing in a damaged home — so calculate it before the season starts.
- Find your percentage on your declarations page and multiply it by your dwelling coverage to get your dollar exposure.
- Build that amount into your emergency savings so you can actually cover it after a storm.
- Weigh the trade-off if you're tempted by a lower premium — a cheaper policy often carries a higher percentage deductible.
- Pair it with flood coverage, since your hurricane deductible does nothing for flood damage — see our guide on whether you need flood insurance in Baton Rouge.
A quick review with a local agent can confirm your exact deductible and whether it fits what you could realistically pay out of pocket.
Know your hurricane deductible before the season?
If you're not sure what you'd actually owe after a named storm, now — not during one — is the time to find out. The team at The Root Agency will confirm your exact hurricane deductible, check that it fits what you could pay out of pocket, and make sure your flood coverage fills the gap. When you're ready, start on our home insurance page or contact your Baton Rouge team, and we'll make sure there are no surprises.
This article is general information, not insurance advice. Deductible terms vary by your specific policy — review your declarations page and talk with a licensed agent.