
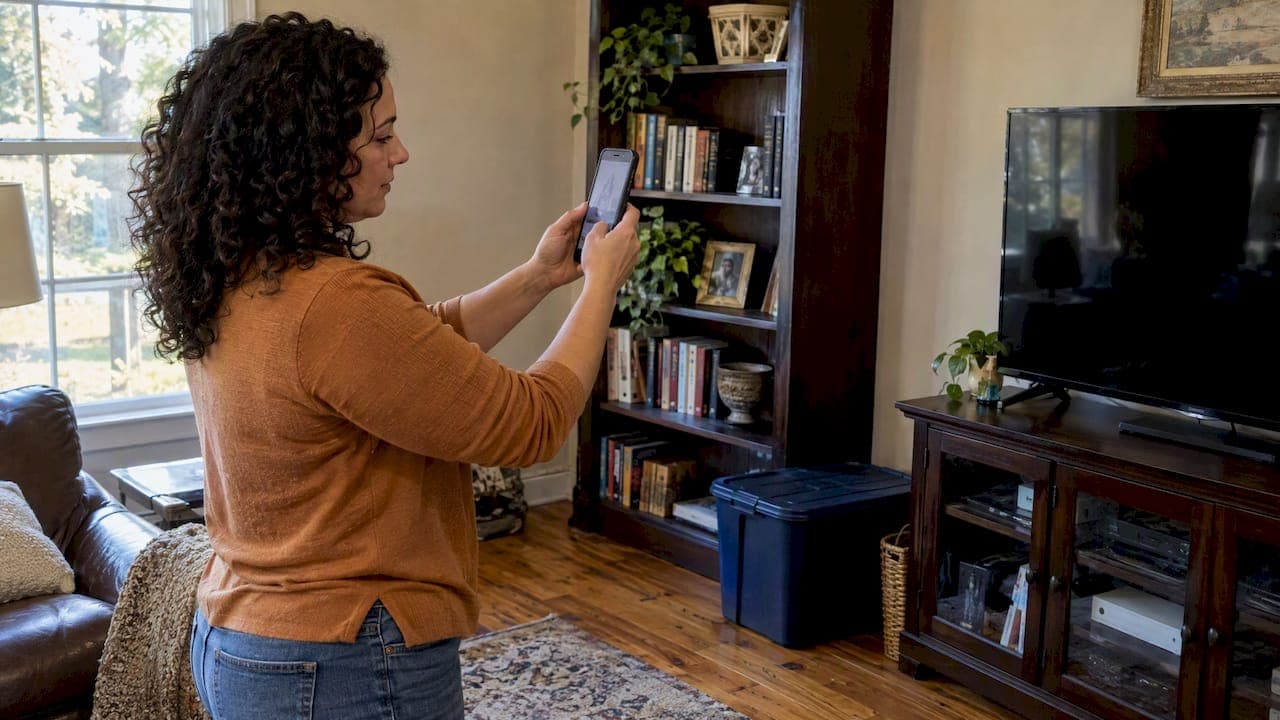
Louisiana Homeowners: Finish Home Inventory in a Weekend With NAIC App

Create a room-by-room photo and video inventory, record serial numbers and receipts for every item, and store a copy offsite where a storm or fire can’t reach it. A home inventory for insurance is a documented list of your belongings and their value, and it exists to speed up your claim and prove what you owned before disaster struck. The fastest ways to start: open the NAIC home inventory app, walk one room with your phone camera, and email yourself the first batch of photos tonight.
TL;DR:
- Ensure your home inventory includes serial numbers, purchase prices, and photos for each item to meet insurer documentation standards.
- Use cloud-based apps like the NAIC home inventory app or printable checklists to streamline organization and sharing with adjusters.
- Keep a copy of your inventory offsite or in cloud storage and test backups twice a year to prevent loss during disasters.
- Record all receipts, appraisals, and supporting documentation for high-value items and attach them to your inventory entries.
- Complete your full-house inventory within a weekend by prioritizing high-value rooms and limiting the time spent in each area.
Table of Contents
- Where to find trusted apps and free templates
- What to record for every item so insurers accept it as proof
- A room-by-room workflow that gets the job done in a weekend
- Where to store your inventory so a disaster can’t erase it
- What to send an adjuster and how to behave during a claim
- Keeping your inventory current without it becoming a chore
- What adjusters actually want to see, and how we help after a storm
- Why a good inventory is resilience, not paperwork
- Let us review your coverage and hold onto your inventory
- FAQ
- Sources
Where to find trusted apps and free templates
You don’t need to build a home inventory from scratch. Several free, vetted tools already exist, and using one of them makes your documentation easier for an adjuster to accept.
The NAIC home inventory app, called myHOME Scr.APP.book, lets you capture images, write descriptions, scan bar codes, and log serial numbers room by room. You can export the finished file and share it directly with us or with your claims adjuster, which matters more than it sounds: a structured export looks organized the moment it lands in an inspector’s inbox. Several state insurance departments, including California and Ohio, publish their own home inventory checklist PDFs that work as paper backups or printable worksheets for readers who prefer pen and clipboard to an app.
If you’d rather build something yourself, a simple spreadsheet paired with a phone camera folder works fine, as does a voice memo app where you narrate room by room and transcribe later; for owners of high-value properties, considering best home insurance Houston options tailored to luxury homeowner needs is especially important. The tradeoff is organization: a dedicated app forces consistent fields (serial number, purchase date, value) while a DIY method only works if you’re disciplined about filling in every column every time.
Before you commit to a method, run it against this short checklist:
- Backup built in: Does the tool sync to the cloud automatically, or will you need to export and upload manually?
- Export format: Can you generate a PDF or spreadsheet that an insurer can open without special software?
- Privacy control: Who else can see the file, and can you lock it with a password?
- Room for detail: Does it have fields for serial numbers and purchase price, or just a photo and a caption?
Pick whichever method you’ll actually finish. A half-completed spreadsheet helps you less than a finished app-based inventory of your three most valuable rooms.
What to record for every item so insurers accept it as proof
Insurers and adjusters look for specific, repeatable details on every line of a claim. Leaving out a field doesn’t just slow things down, it can mean a lower payout or a request for more proof before a check gets cut.
For each item, record:
- Item name and category (living room sofa, kitchen appliance, jewelry).
- Room location, so the inventory mirrors how an adjuster will walk the house.
- Brand, model, and serial number, plus any identifying marks like engravings or custom finishes.
- Purchase date and purchase price, even an approximate one.
- Current estimated value, which may differ from what you paid.
- Receipts, appraisals, or certificates, especially for jewelry, art, or collectibles.
- Photos from two angles: one wide shot showing the item in context and one close-up on the serial number or maker’s mark.
Ready photographing and videotaping belongings, recording make, model, and serial numbers, and storing the finished inventory offsite so it survives whatever damaged the house. That guidance lines up with what we see after Louisiana storms: the homeowners whose claims move fastest are the ones who can hand an adjuster a dated photo next to a receipt, not a verbal description of what used to be in the closet.
For anything individually worth more than a few hundred dollars, a formal written appraisal is worth the trip. Jewelry, fine art, firearms, and musical instruments often need a specialist’s signature before an insurer will pay out their full value rather than a generic estimate.
Pro Tip: Photograph the serial number plate and the full item in the same sequence of shots so the two images stay linked in your camera roll without extra labeling.

A room-by-room workflow that gets the job done in a weekend
Most homeowners quit halfway through a home inventory because they try to document everything at once. Breaking it into rooms, with a time limit per room, keeps the project from stalling.
- Start with your highest-value rooms first. Master bedroom closets, home offices, and any room holding jewelry, electronics, or collectibles go before the linen closet.
- Set a 20-minute timer per room. Walk the space once with your phone recording video, narrating what you see (“this is the oak dresser, purchased around 2019”), then go back for close-up stills of serial numbers and tags.
- Use your phone’s barcode scanner for electronics and appliances where the model number is buried on a sticker. Most inventory apps, including the NAIC app, accept a scanned barcode as a shortcut to the model field.
- Dictate notes with voice-to-text rather than typing while you’re holding a camera in the other hand, then clean up the text later.
- Upload to the cloud before you move to the next room, not at the end of the day, so a dead battery or dropped phone never costs you a finished room’s worth of work.
- Attach receipts to each entry as you find them, even if that means a second pass through filing cabinets and inbox folders a few days later.
One stat worth knowing: according to NAIC consumer research, many Americans do not have a list of their own possessions. That gap is exactly what shows up after a hurricane, when a homeowner is trying to recall the contents of a flooded garage from memory instead of a file.
Most homeowners can finish a full-house inventory in a single weekend at this pace, two rooms a day on top of a normal schedule. The point isn’t speed for its own sake, it’s finishing before you need it.
Where to store your inventory so a disaster can’t erase it
The single biggest mistake we see after storms is a homeowner who built a perfect inventory and left the only copy on a laptop that flooded along with everything else. Offsite storage is not optional.
- Cloud storage (Google Drive, Dropbox, iCloud) keeps your file accessible from any device with internet, which matters when you’re displaced and working from a hotel room.
- Emailed copies to yourself or a trusted family member outside Louisiana create a second, independent backup that survives a regional outage.
- A safe-deposit box holds a printed or flash-drive copy, though you should confirm your bank’s access rules for a spouse or executor ahead of time, since some banks restrict access during an emergency.
- A trusted relative out of state can hold a copy too, which is especially useful if local infrastructure is down for days after a major storm.
Name your files clearly (“Inventory_LivingRoom_2026”) and set sharing permissions so only you and the people you choose, including us when you’d like a policy review, can open the file. Ready.gov’s guidance on documenting and insuring your property specifically recommends storing your inventory somewhere other than the property itself for exactly this reason.
Pro Tip: Test your backup twice a year by opening it on a different device, your phone instead of your laptop, to confirm the file actually syncs and isn’t just sitting in a broken upload.
What to send an adjuster and how to behave during a claim
A finished inventory only helps if you hand it over in a form an adjuster can use quickly. Send a tidy packet, not a pile of loose photos.
- Export your inventory as a PDF or a zipped folder of photos, videos, and the itemized list together, rather than sending dozens of individual email attachments.
- Include receipts and appraisals in the same packet, labeled by item so the adjuster doesn’t have to match them manually.
- Preserve damaged items until an adjuster has inspected them, as long as keeping them doesn’t create a health or safety risk. FEMA specifically advises photographing and videotaping flood-damaged items, recording serial numbers, and keeping receipts before discarding anything, and to contact a repair service first when possible.
- Log every emergency purchase and temporary repair with a date and a receipt. Ready notes that documenting temporary repairs and keeping those receipts is a frequently overlooked step, and it’s often the difference in getting reimbursed for additional living expenses.
- Keep your inventory updated as items are replaced, since the same checklist recommends refreshing the list after settlements so your coverage reflects what you actually own going forward.
Your inventory doesn’t just prove ownership, it maps directly onto how personal property coverage pays out, line item by line item, and supports additional living expense claims when you’re displaced from your home during repairs. If a claim gets denied or you disagree with a settlement amount, most disaster assistance programs including FEMA have a formal appeals process with its own timeline, so don’t assume the first number you hear is final.
Keeping your inventory current without it becoming a chore
An inventory from three years ago is better than nothing, but it’s not what you want in hand during a claim. Build a simple maintenance rhythm instead of treating this as a one-time project.
- Do a full review once a year, ideally around the same month every year so it becomes a habit rather than a surprise task.
- Update immediately after any major purchase, new furniture, electronics, or jewelry, while the receipt is still easy to find.
- File receipts the week you get them, not months later when half of them have been thrown out with junk mail.
- Keep a short change log, even a single line noting what you added or removed and when, so you’re not guessing later whether an item was ever documented.
An outdated inventory can also mean outdated coverage. If your home’s contents have grown in value since you last updated your limits, your policy’s replacement cost calculation may no longer match what’s actually inside the house, which is part of why we recommend pairing an accurate inventory with a coverage check rather than treating the two as separate tasks.
What adjusters actually want to see, and how we help after a storm
A claims-ready inventory, to an adjuster, looks like a packet they can process without chasing you for more information: photos tied to receipts, serial numbers legible, values reasonable and documented. Organized evidence doesn’t just speed a claim, it reduces the back-and-forth that drags a settlement out for weeks.

Steve Root has spent more than 20 years helping Louisiana families recover from hurricanes, floods, and the paperwork that follows, building on a 40-year family legacy in Louisiana insurance. After a major storm, our mobile catastrophe response unit deploys directly into affected neighborhoods so homeowners aren’t stuck navigating a claim entirely over the phone. We also offer bilingual support in English and Spanish and 24/7 claims assistance, because disasters don’t wait for business hours and neither should the help that follows them.
When you share your inventory with us ahead of a storm season, our team already knows what’s in your home before anything happens to it. That head start matters when a hurricane makes landfall and hundreds of claims hit an adjuster’s desk at once: a homeowner who pre-shared a complete, dated inventory is simply easier to help first.
A homeowner who can hand an adjuster a dated photo next to a receipt moves through a claim faster than one working from memory.
— Steve Root
Why a good inventory is resilience, not paperwork
Think of a home inventory less as a filing task and more as part of your household’s disaster plan, right alongside flood coverage and an evacuation route. The homeowners who recover fastest after a storm aren’t the ones who found the cheapest policy five years ago. They’re the ones who had proof of what they owned and a local agent who picked up the phone the moment things got bad.
Coverage without documentation is a guess. Documentation without the right coverage is a well organized disappointment. Start one room today, photograph it, back the file up offsite, and you’ve already done more than most homeowners ever will.
— Steve Root
Let us review your coverage and hold onto your inventory
We’ll review your home insurance policy free of charge and factor your inventory directly into that conversation, because a policy that matched your home’s value five years ago may not match it now. Call us or request a review, and when you do, email your finished inventory, or just your photos and receipts so far, before the appointment so we can look at both together.
Attach whatever you have: photos, a spreadsheet, receipts, even a half-finished NAIC app export. We offer bilingual service in English and Spanish, 24/7 claims assistance, and a mobile catastrophe response unit that deploys directly into affected neighborhoods during Louisiana storms. That kind of hands-on support is part of why we carry a reputation few agencies in this state can match.
| What you get | Detail |
|---|---|
| Free policy review | Covers your home insurance against your current inventory and replacement costs |
| Bilingual claims support | Available in English and Spanish, 24/7 |
| Catastrophe response | Mobile unit deploys directly to storm-affected neighborhoods |
| Starting point | Explore home insurance coverage options built for Louisiana homes |
- Call or request a quote to start your review.
- Email or upload your inventory, even an unfinished one, before your scheduled call.
- Bring receipts for any high-value items so we can flag coverage gaps early.
Visit our home insurance page to get started, or reach out directly so we can walk through your policy together.
FAQ
How do I make a home inventory list for insurance?
Walk through your home room by room with your phone camera, photographing and video recording each item while narrating details like brand, model, and approximate purchase date. Use a free tool like the NAIC home inventory app to keep serial numbers, receipts, and photos organized in one exportable file, then store a copy offsite.
Is there a free home inventory app?
Yes, the NAIC’s myHOME Scr.APP.book is a free app that lets you capture images, descriptions, bar codes, and serial numbers, then export the finished inventory to share with an insurer. Several state insurance departments also publish free printable checklist templates as an alternative to an app.
How do I itemize items for an insurance claim?
List each item with its name, room, brand, model, serial number, purchase date, purchase price, and current estimated value, supported by a photo and, when available, a receipt or appraisal. FEMA recommends photographing and videotaping damaged items and keeping receipts and serial numbers before discarding anything, which gives an adjuster everything needed to process the line item.
Should I keep an inventory of everything I own for insurance purposes?
Yes, a documented inventory of your belongings speeds up claims and helps prove both ownership and value after a loss, rather than relying on memory during an already stressful time. Ready.gov’s guidance on documenting and insuring your property recommends this as a standard part of disaster preparedness, not just a claims tool.
How often should I update my home inventory?
Review your full inventory at least once a year and update it immediately after any major purchase, renovation, or disposal of belongings. Keeping it current ensures your coverage limits still reflect what you actually own, which matters most the day you need to file a claim.