
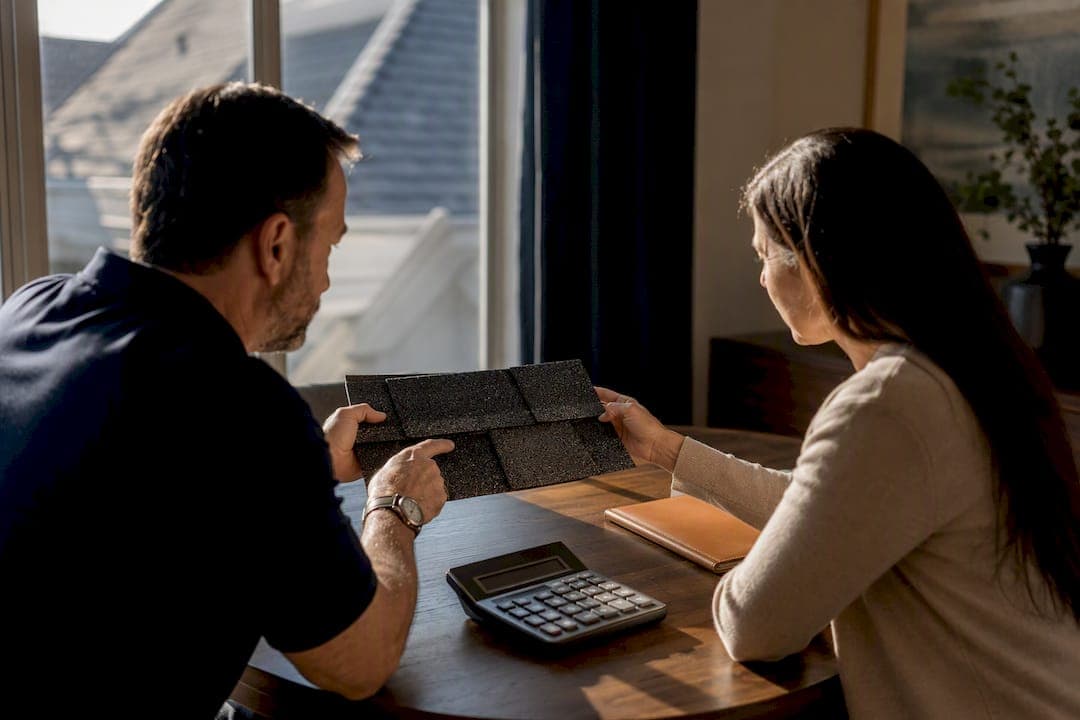
Don’t Lose Recoverable Depreciation: Louisiana Roof Payment Schedule

A roof payment schedule endorsement typically shifts your roof surfacing from replacement cost value to an age-based actual cash value settlement, which means your first check after storm damage will be smaller than the cost to replace the roof. The single most important thing you can do right now is pull out your declarations page, find the endorsement by name, and call your agent to ask what documentation restores the depreciation the insurer held back.
TL;DR:
- Roof payment schedule endorsements tie payouts to the roof’s age and condition, often settling wind and hail damage at actual cash value rather than replacement cost.
- The endorsement can cause you to lose recoverable depreciation if you miss deadlines, which typically range from six months to a year after repairs are completed.
- To maximize payments, homeowners must promptly document repairs, submit detailed invoices, and request depreciation calculations in writing before deadlines pass.
- Insurers often exclude cosmetic damage, pre-existing wear, and matching costs from coverage, especially on older or specialty roofs like tile or slate.
- Reviewing your policy before storm season and verifying the endorsement details can help prevent surprises and facilitate faster claims processing.
Table of Contents
- What a roof payment schedule endorsement actually is
- How the endorsement changes your settlement math
- Recognizing the language insurers actually use
- What to do the moment you find roof damage
- Louisiana’s claim timelines and homeowner protections
- How The Root Agency helps when this endorsement applies
- Roofing materials change how the endorsement applies
- What these endorsements typically do not cover
- Disputing a payment schedule amount you believe is wrong
- What this means for paying your roofing contractor
- Coverage is worth more than the smallest premium
- Getting your policy reviewed before the next storm
- Sources
- FAQ
What a roof payment schedule endorsement actually is
A roof payment schedule endorsement is a policy add-on that changes how your insurer pays for roof damage. Instead of paying to replace the roof at today’s prices, the endorsement ties your payout to the roof’s age and condition, similar to how a used car is valued rather than a new one. Insurers add these endorsements because roofs wear out faster than the rest of the house, and older roofs cost more to insure at full replacement value.
You will not always see the phrase “roof payment schedule” printed in plain English. Look instead for these common labels:
- Roof surfacing payment schedule endorsement
- Roof ACV endorsement or “roof actual cash value” clause
- References to HO-04-93 or similar ISO form numbers
- Language stating roof surfacing is “settled at actual cash value” for wind or hail
The endorsement usually sits near the back of your policy packet, but its name and form number appear on your declarations page under endorsements or forms attached. If you cannot find it, our home insurance page walks through where Louisiana homeowners typically find these clauses on an Allstate policy.
How the endorsement changes your settlement math
Most Louisiana homeowners carry replacement cost value, or RCV, coverage on their dwelling. Under NAIC guidance, RCV policies typically pay in two stages: an initial payment based on actual cash value, followed by a second payment covering recoverable depreciation once you finish repairs and submit proof. That second check is where a roof payment schedule endorsement causes problems, because it can carve the roof surfacing out of that two-stage process and settle it at ACV only, with little or no depreciation recovered even after the work is done.
Here is a simplified illustration. Suppose your roof would cost a significant sum to replace today, and it is several years old with an expected lifespan typical for such roofs; the insurer may depreciate its value accordingly, cutting the initial payment to a reduced amount minus your deductible. Under a normal RCV roof, you would submit your contractor’s final invoice and recover most or all of that withheld $7,500. Under a roof payment schedule endorsement, that recoverable portion may be permanently reduced or eliminated for wind and hail losses, depending on the exact endorsement wording.
Recoverable depreciation deadlines are easy to miss. The NAIC Post-Disaster Claims Guide notes that time limits to claim recoverable depreciation commonly range from six months to a year, though states can extend those windows after major disasters. Missing that window means the money you were owed simply expires.
To protect recoverable depreciation where it still applies, you generally need to:
- Complete repairs with a licensed contractor
- Submit the final, itemized invoice showing work performed
- Provide dated photos confirming completion
- Request the depreciation payment in writing before your policy’s deadline
Recognizing the language insurers actually use
The exact wording matters more than the general idea. Primary ISO endorsement language modifies the loss settlement condition so that losses to roof surfacing caused by windstorm or hail are settled at actual cash value, even when the rest of your dwelling coverage remains RCV. This clause often reads as a short paragraph tucked among other endorsements, easy to skim past.
When reviewing your declarations, watch for:
- A separate line item labeled “roof surfacing” with its own settlement basis
- Wording that singles out “wind” or “hail” losses for different treatment than fire or other perils
- A distinct wind/hail or hurricane deductible, often a percentage rather than a flat dollar amount
- Any reference to “cosmetic damage exclusion” attached to the same endorsement
Louisiana homeowners frequently carry a separate hurricane or named-storm deductible on top of the roof schedule, and our breakdown of deductible types explains how those two provisions interact and why they can stack against you in the same claim.
What to do the moment you find roof damage
Getting recoverable depreciation paid depends on doing things in the right order and keeping records at every step.
- Notify your insurer immediately and get your claim number and adjuster’s direct contact information in writing.
- Document everything before cleanup, including timestamped photos, video walkthroughs, and a written contractor estimate.
- If your dwelling carries RCV coverage, complete repairs promptly and submit the final invoice, completion photos, and a signed completion statement to trigger the depreciation payment.
- Request the adjuster’s itemized depreciation calculation in writing so you can see exactly how the roof was valued and challenge errors.
- Consider a public adjuster or a call to the Louisiana Department of Insurance if the insurer delays or the numbers do not add up.
Pro Tip: Keep a single folder, physical or digital, with every photo, contractor contract, and email tied to the claim. Adjusters and courts both respond better to a clean paper trail than to memory.
Louisiana’s claim timelines and homeowner protections
Louisiana law gives homeowners more leverage than many states offer. Insurers must begin adjusting a claim within 14 days of notice and pay the amount due within 30 days after you submit satisfactory proof of loss, and delays without a reasonable basis can trigger penalties against the insurer.
Louisiana requires insurers to include contractor overhead and profit in loss payments when multiple trades are reasonably foreseeable, under La. R.S. 22:1892(F), according to a summary of Louisiana insurance coverage basics. If your estimate leaves out overhead and profit despite needing several contractors, that omission can itself be evidence of underpayment.
Practical ways to use these protections:
- Cite the 14-day and 30-day windows in writing if your insurer goes silent
- Ask directly whether overhead and profit were included in the estimate
- Send a written notice before threatening legal action, since Louisiana courts often expect that step first
- Keep these deadlines in mind alongside your recoverable depreciation window, since both clocks run at the same time
How The Root Agency helps when this endorsement applies
Reviewing an endorsement like this is exactly the kind of work Steve Root has done for Louisiana families for more than 20 years. When a roof payment schedule endorsement is part of your policy, our team can:
- Pull your declarations page and identify the exact endorsement and form number
- Request the itemized depreciation calculation directly from the carrier on your behalf
- Coordinate with your contractor so invoices and completion proof reach the insurer correctly
- Advise on when a public adjuster makes more sense than continuing through the standard claims process
With a strong focus on client service and a mobile catastrophe response unit that deploys after major storms, the agency builds its process around being reachable when a claim gets complicated, not just when a policy gets sold.
Roofing materials change how the endorsement applies
Not every roof type gets treated the same way under a payment schedule endorsement, and the material on your house affects both your depreciation curve and your options after damage. Asphalt shingle roofs, the most common in Louisiana, tend to depreciate the fastest and are the roofs most often targeted by these endorsements because they wear out in 15 to 20 years. Metal roofs and fortified roofs built to Louisiana’s wind mitigation standards sometimes qualify for more favorable settlement terms or premium credits, since insurers expect a longer usable life and less storm damage.
Tile and slate roofs carry their own complications, since matching materials after a partial loss can be difficult, and some endorsements address that with separate matching provisions. Flat or low-slope roofs, common on additions or garages, are sometimes excluded entirely from a roof payment schedule and settled under different terms because their failure patterns differ from pitched roofs.

If your home has a fortified roof or recent upgrade, it is worth asking your agent whether that improvement changed your endorsement terms, since insurers do periodically adjust roof schedules when a homeowner installs a higher-rated roofing system. Mobile and manufactured homes also carry distinct roof considerations, and our guide to mobile home insurance in Louisiana covers how roof endorsements apply differently to those structures.
What these endorsements typically do not cover
Roof payment schedule endorsements come with limitations that catch homeowners off guard after a claim is already underway. Cosmetic damage, such as discoloration or minor granule loss that does not affect function, is commonly excluded even when a full slope shows visible wear. Many endorsements also exclude cases where the roof was already past its expected lifespan before the loss occurred, since insurers treat that damage as pre-existing wear rather than storm-caused loss.
Matching is another common gap. If only part of your roof is damaged and the original shingles are no longer manufactured, some endorsements limit payment to the damaged sections only, leaving you to pay out of pocket for a uniform look. Maintenance-related issues, including damage from lack of upkeep or unresolved prior leaks, typically fall outside any endorsement’s scope regardless of how the roof is otherwise valued.
Homeowners should also check whether the endorsement carves out coverage for detached structures with separate roofs, such as sheds or detached garages, since those sometimes follow different settlement rules than the main dwelling. Reading the exclusions section alongside the endorsement itself, rather than assuming it mirrors your main policy, is the only reliable way to know what is actually excluded.

Disputing a payment schedule amount you believe is wrong
If your insurer’s roof valuation feels off, you have real options before accepting the check. Start by requesting the adjuster’s full itemized estimate in writing, including the depreciation percentage applied and the reasoning behind the roof’s assigned age and remaining life. Compare that estimate against your own contractor’s written assessment, since a documented gap between the two is often the strongest tool in a dispute.
If the insurer will not revise the estimate, Louisiana homeowners can request an appraisal, a process built into most policies that lets each side hire an independent appraiser, with a neutral umpire settling any disagreement between them. This route tends to be faster and less expensive than litigation and often resolves valuation disputes without a lawyer.
For more serious underpayment, especially where overhead and profit were omitted despite multiple trades being needed, a written demand citing La. R.S. 22:1892 can prompt a revised settlement, since Louisiana law explicitly requires that inclusion when contractor services are reasonably foreseeable. If delays or lowball estimates continue, filing a complaint with the Louisiana Department of Insurance puts the dispute on the record and can accelerate a resolution.
What this means for paying your roofing contractor
A roof payment schedule endorsement does not just affect your relationship with the insurer. It directly shapes how you pay the contractor doing the work. Because the initial ACV check is smaller, many homeowners find they need to cover a larger upfront gap before the recoverable depreciation payment arrives, which means the contract terms you sign matter more than usual.
Ask your contractor to structure payments in stages tied to project milestones rather than requiring the full amount upfront, since that protects you if the depreciation payment is delayed or disputed; learn more about insurance quote follow up to help manage these timing issues effectively. Make sure the final invoice is itemized clearly enough to satisfy your insurer’s documentation requirements, since a vague invoice is one of the most common reasons recoverable depreciation payments get held up or denied. Keeping a signed contract, a payment schedule, and every invoice in one file also protects you if a dispute over the endorsement drags on longer than the repair itself.
Coverage is worth more than the smallest premium
Homeowners who have filed a real claim after a hurricane understand this instinctively: the cheapest policy and the cheapest roof endorsement often cost the most in the end. A roof payment schedule endorsement is not inherently unfair, but it rewards homeowners who read their declarations, document everything, and have an agent who picks up the phone when the depreciation check does not show up.
— Steve Root
Getting your policy reviewed before the next storm
Most homeowners discover a roof payment schedule endorsement only after filing a claim, which is the worst possible time to learn your roof is on an age-based schedule. A policy review before storm season catches this while you can still make an informed decision about your coverage.
The agency sits down with Louisiana homeowners and walks through the declarations page line by line, including any roof endorsement, wind/hail deductible, and the difference between ACV and RCV on specific policies. If a claim is already in progress, help is available to identify the endorsement, request the itemized depreciation breakdown from the carrier, and coordinate the paperwork contractors need to submit. Bilingual staff and 24/7 claims support aim to ensure clients are never stuck waiting until Monday to ask a question that matters now.
- Full policy and endorsement review before you ever file a claim
- Direct coordination with adjusters on depreciation calculations
- Local support from a mobile catastrophe response unit after major storms
- Bilingual, 24/7 claims assistance in English and Spanish
If you want a straight answer about what your roof endorsement actually says, request a home insurance review with The Root Agency and we will walk through your declarations page together.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Rebuilding After a Storm: Know the difference between replacement cost and actual cash value when it comes
- Disputevoice
FAQ
What is a roof payment schedule endorsement?
A roof payment schedule endorsement is a policy provision that settles roof surfacing losses based on the roof’s age rather than its full replacement cost. It typically applies to wind and hail damage and can significantly reduce your initial claim payout compared to a standard replacement cost policy.
What is an HO-15 endorsement?
HO-15 is a broader “open perils” endorsement that expands personal property coverage on an HO-3 policy, and it is separate from roof-specific ACV endorsements. If you are looking specifically for roof settlement language, check your declarations for form numbers tied to roof surfacing rather than HO-15.
What is the roof payment schedule?
The roof payment schedule refers to the age-based depreciation table an insurer uses to calculate how much of your roof’s value has worn away before a loss occurs. Older roofs are depreciated more heavily, which lowers the actual cash value payout under NAIC guidance on ACV versus RCV.
What is an insurance endorsement schedule?
An endorsement schedule is simply the list of endorsements attached to your policy, shown on your declarations page along with their form numbers and effective dates. Reviewing this schedule with your agent is the fastest way to confirm whether a roof payment schedule endorsement applies to your home.
How do I get recoverable depreciation paid after a roof claim?
You generally need to complete the roof repair, then submit the final contractor invoice, completion photos, and a signed statement to your insurer. The NAIC Post-Disaster Claims Guide notes that recoverable depreciation deadlines commonly range from six months to a year, so submitting paperwork promptly matters.