
Louisiana: Keep Control, Avoid 60–80% Higher Mortgage Life Insurance
For most homeowners, a level term life policy you own outright is the better way to protect a mortgage; lender-sold mortgage protection insurance is a narrow exception when health issues block you from qualifying for personal coverage. The reasoning comes down to three things: you control who gets the money, healthy applicants pay less per dollar of coverage, and full underwriting up front means no surprises when your family needs the payout most.
TL;DR:
- Lender-sold mortgage protection insurance often costs 60% to 80% more than a comparable level term life policy for healthy applicants.
- Mortgage protection insurance’s benefit decreases over time and usually cancels if you refinance or switch lenders, whereas term life benefits stay level and portable.
- Fully underwritten term policies verify health before issuing coverage, reducing the risk of claim denial, unlike many MPI policies that underwrite after a claim.
- Protect your family by choosing a level term policy matching your mortgage’s length and amount, rather than relying on lender coverage that erodes or cancels.
- Comparing total premiums over the entire term, not just initial quotes, ensures you understand the true long-term cost difference.
Table of Contents
- What Is Life Insurance for a Mortgage, and How Does MPI Differ From Term Life?
- Weighing the Pros and Cons of Each Option
- What Does Mortgage Life Insurance Actually Cost?
- The Underwriting Risk Most Homeowners Never Ask About
- How to Choose: The Questions to Ask Before You Sign
- Steve Root and The Root Agency: Local Experience That Matters
- How The Root Agency Helps You Protect Your Mortgage the Right Way
- Sources
- FAQ
What Is Life Insurance for a Mortgage, and How Does MPI Differ From Term Life?
Mortgage protection insurance and personal term life insurance both promise to pay off a home loan if you die. How they get there is where the similarities stop.
MPI is typically sold by your lender or a company partnered with them, right at closing or shortly after. The lender is almost always the named beneficiary, and the payout usually declines over time. As you pay down principal, your coverage shrinks with it, even though your premium often stays flat. That structure means you’re paying the same amount for less protection every year you own the policy.
Personal term life insurance works differently. You choose the death benefit, you name the beneficiary, and that benefit stays level for the length of the term, whether that’s 10, 20, or 30 years. Your family, not the bank, decides how the money gets used. They might pay off the mortgage. They might cover two years of income first and refinance later. That flexibility is not a minor feature.
Portability matters just as much. A term policy you own follows you if you refinance, sell, or switch lenders. Coverage tied to your mortgage through the lender typically cancels the moment you refinance or pay off the loan, leaving you to requalify for new coverage, often at an older age and a higher rate.
Quick comparison:
- Beneficiary: MPI pays the lender directly; term life pays whoever you name.
- Benefit shape: MPI often decreases with your loan balance; term life stays level.
- Portability: Term life moves with you; lender-tied coverage usually ends at refinance.
- Who decides how funds are used: With term life, your family does. With MPI, the bank does.
Weighing the Pros and Cons of Each Option
Neither product is universally wrong. The trade-offs just land very differently depending on your health, your timeline, and how much control you want over the outcome.
- MPI advantages: Simplified or guaranteed issue underwriting, meaning some applicants with health conditions get approved when a fully underwritten policy might deny them. It’s also convenient, since it’s offered right at the closing table with no separate application.
- MPI drawbacks: Higher cost per dollar of coverage, a benefit that shrinks as your balance drops, a lender as sole beneficiary, and in many cases, underwriting that happens after you file a claim rather than before you buy the policy.
- Term life advantages: Lower cost for healthy applicants, a level benefit that doesn’t erode, full control over who receives the payout, and coverage that stays with you through a refinance or move.
- Term life drawbacks: Stricter underwriting up front, which may include a medical exam or a detailed health questionnaire, and an approval process that takes days or weeks rather than happening instantly at closing.
What Does Mortgage Life Insurance Actually Cost?
Cost is where the gap between these two products becomes hard to ignore. Lender-sold mortgage protection insurance can run roughly 60% to 80% higher than a comparable term life policy for a healthy applicant seeking the same amount of coverage.
The Premium Gap: A healthy 40-year-old shopping for coverage to match a mortgage balance will typically pay far less for a fully underwritten term policy than for the equivalent lender-sold MPI plan, according to Bankrate’s analysis. Over a 20 or 30-year term, that difference compounds into thousands of dollars.
Part of the reason is how each product prices risk. MPI premiums are often set against your original mortgage amount and stay fixed even as your coverage declines. Term life is priced once, for a level benefit you choose, and that price doesn’t move unless you change the policy.
Here’s how to compare the two properly instead of taking the lender’s offer at face value:
- Request an independent term life quote for a death benefit that matches your current mortgage balance.
- Compare total premium costs across 10, 20, and 25-year terms, not just the first-year price.
- Run your numbers through a mortgage calculator to see how your outstanding balance shrinks over time, then decide whether a level or decreasing benefit fits your actual risk.
The Underwriting Risk Most Homeowners Never Ask About
The most overlooked danger in mortgage protection insurance isn’t the price. It’s timing. Many MPI policies use simplified or guaranteed-issue underwriting, which sounds like a benefit until you understand what it defers.
Some of these policies check your health history only after a claim is filed, not before you start paying premiums. That’s called post-claim underwriting, and it means your family could pay premiums for years, then have a claim denied because of a pre-existing condition that surfaces during the insurer’s after-the-fact review. A fully underwritten term policy checks your health once, at the start, so an approved claim stays approved.
Before you sign anything a lender hands you at closing, verify these points directly:
- Who is named as the beneficiary, and can that be changed?
- Is underwriting completed before the policy issues, or only if a claim is filed?
- Does the policy cancel automatically if you refinance or switch lenders?
- Is there a refund if you cancel within the first year?
Pro Tip: If a fully underwritten term policy is still in process, it’s reasonable to accept short-term lender coverage as a bridge. Just cancel it the moment your term policy is issued so you’re not paying for two policies that do the same job.
How to Choose: The Questions to Ask Before You Sign
Choosing the right coverage for your mortgage isn’t complicated once you know what to ask. It just requires asking before you sign, not after a claim gets denied.
- Match your term length to your mortgage. A 30-year mortgage generally calls for a 30-year term policy, not a 20-year one that expires while you still owe a balance.
- Consider coverage beyond the mortgage. A policy sized only to your loan balance covers the house. A policy sized to cover the mortgage plus a year or two of income replacement protects your family’s whole financial picture.
- Verify portability in writing. Ask whether the policy stays in force if you refinance or sell and buy again.
- Get quotes from more than one source. Compare what your lender offers against an independently underwritten policy before you decide.
- Ask your agent directly: Who is the beneficiary? When does underwriting happen? What happens to this policy if I refinance next year?
Pro Tip: Beneficiary control and portability should be the two deciding factors, not the premium quoted at the closing table. A slightly higher payment today for a policy that stays with you through life changes is usually the better trade.
Steve Root and The Root Agency: Local Experience That Matters
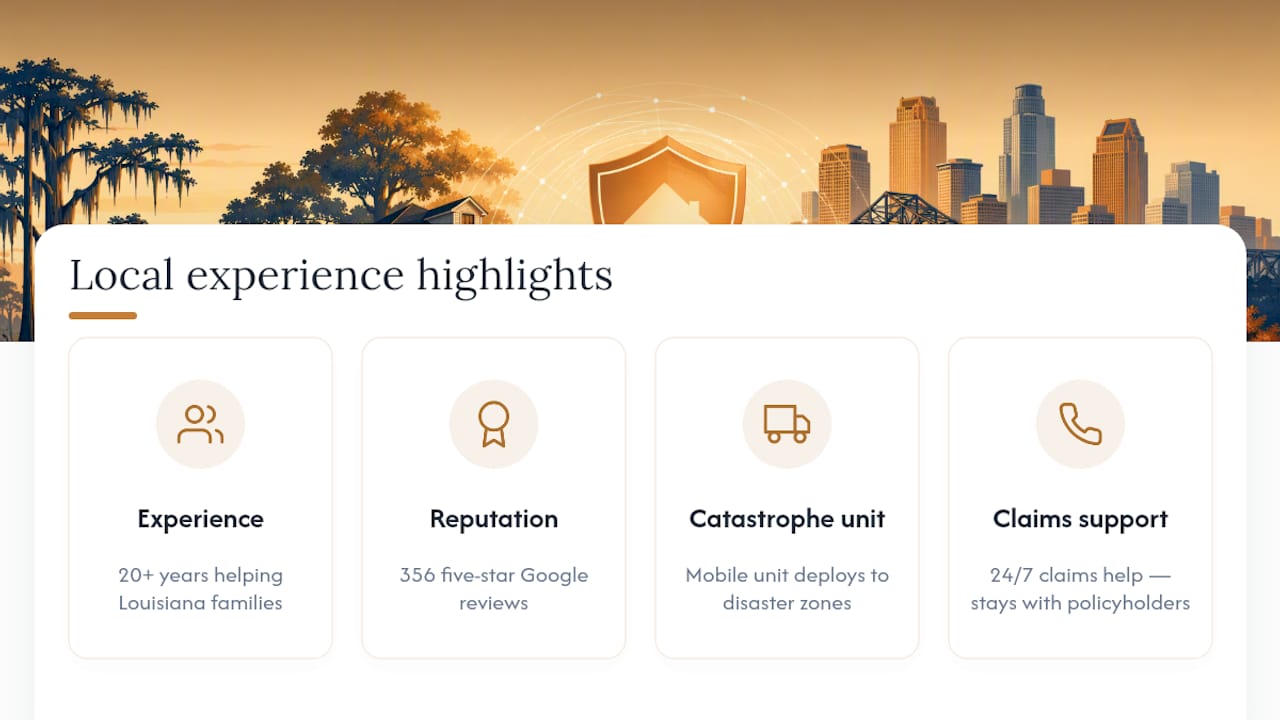
I’ve spent more than 20 years helping Louisiana families make exactly this decision, and I can tell you the difference shows up years later, not at the moment you sign the paperwork. It shows up when a claim gets filed and someone has to answer the phone.
The Root Agency has built its reputation on being that voice on the other end. We carry 356 five-star Google reviews, and we’re the agency that stayed in Louisiana with a mobile catastrophe response unit that deploys directly to disaster zones when storms hit, rather than leaving policyholders to navigate a claim alone. That same philosophy applies to life insurance. A policy review at refinance, a real conversation about whether your coverage still fits your mortgage and your family, and 24/7 claims support when it matters most. That’s not an add-on. It’s the protection you’re actually paying for.
— Steve Root
How The Root Agency Helps You Protect Your Mortgage the Right Way
Choosing between mortgage protection insurance and personal term life shouldn’t happen in a rush at the closing table, and it shouldn’t happen without someone local reviewing your specific numbers first.
The Root Agency, an Allstate exclusive agency built on Steve Root’s 40-year family legacy in Louisiana insurance, helps homeowners across Louisiana and Mississippi compare term and whole life options against whatever a lender has offered, so you know exactly what you’re buying before you sign. We’ll walk through your mortgage balance, your term length, and your family’s income needs, then match you with coverage that’s portable, properly underwritten, and priced fairly for your health. Bilingual service in English and Spanish means language is never a barrier to getting this right, and our 24/7 claims support means someone answers when your family needs us most. Visit our life insurance page to request a quote, or call (225) 926-0160 to schedule a policy review with an agent who has spent two decades doing exactly this for Louisiana families. You can also browse our full range of coverage options if you’re protecting more than just your mortgage.
Sources
The figures and guidance in this article draw on established consumer finance research. Bankrate provided cost comparison data between mortgage protection insurance and term life. Investopedia explained underwriting structure and portability differences. MoneyGeek detailed simplified and guaranteed-issue underwriting practices. MarketWatch offered consumer guidance on comparing quotes. The Consumer Financial Protection Bureau also provides independent guidance on distinguishing lender-sold insurance products from personal coverage.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- Mortgage protection insurance vs. life insurance | Bankrate
- Why you don’t need mortgage life insurance | Investopedia
FAQ
Is Mortgage Life Insurance Worth It?
For most healthy homeowners, a personal term life policy is usually a better choice than lender-sold mortgage protection because it costs less per dollar of coverage and keeps the beneficiary decision in your family’s hands. MPI can be worth considering if health issues prevent you from qualifying for a fully underwritten policy.
How Much Does Mortgage Life Insurance Usually Cost?
Lender-sold mortgage protection insurance can cost roughly 60% to 80% more than a comparable term life policy for a healthy applicant seeking the same coverage amount.
Can You Have Life Insurance on a Mortgage?
Yes. You can either accept lender-offered mortgage protection insurance at closing or buy a personal term life policy sized to your mortgage balance, and for most healthy buyers, the personal policy is the stronger choice.
What Life Insurance Is Best for a Mortgage?
A level term life policy that you own and control, sized to match your mortgage term and balance, is generally the best fit because it stays with you through a refinance and pays your named beneficiary directly. Working with a local agent to size that coverage correctly, something The Root Agency does as part of every policy review, helps make sure the number matches your actual loan and income needs.