
How FEMA Flood Maps Work and Why They Matter to You
FEMA flood maps show where floodwater is statistically most likely to reach during a major storm, and they set the rules that insurers, lenders, and local governments use to manage risk. The maps are officially called Flood Insurance Rate Maps (FIRMs), and they carry real weight: they decide whether your mortgage lender can require flood insurance, whether your parish or city will issue a building permit, and how your elevation compares to the water levels engineers expect in a serious flood.
Here’s what that means in practice for a property owner:
- FEMA produces and maintains these maps through the National Flood Insurance Program (NFIP).
- You can look up your exact parcel on the Flood Map Service Center (MSC), the only source that reflects the current, legally effective map.
- The zone your home falls in determines whether flood coverage is mandatory, optional, or simply smart given the storm history in your part of the country.
If you own property anywhere near a bayou, river, or coastline, understanding this system isn’t optional homework. It’s the difference between knowing your real exposure and finding out the hard way after the water recedes.
Key Takeaways
FEMA flood maps assign every property a zone based on statistical flood probability, and that zone determines your insurance obligations, your building requirements, and how much protection you actually need.
| Point | Details |
|---|---|
| Confirm your zone officially | Use the Map Service Center rather than a real estate listing or third-party viewer for your legal flood determination. |
| Understand BFEs before building | Base Flood Elevations on your FIRM determine both insurance rates and construction requirements in high-risk zones. |
| Know the 90-day window | Communities and property owners can submit technical data to challenge preliminary maps within 90 days before adoption. |
| Insure even outside the SFHA | Roughly a quarter of NFIP claims come from lower-risk zones, so “not required” doesn’t mean “not at risk.” |
| Get an expert map review | The Root Agency helps Louisiana property owners interpret FIRMs, gather LOMC documentation, and choose flood coverage that matches real exposure. |
Table of Contents
- How FEMA Flood Maps Work: The Core Products You Need to Know
- How FEMA Creates Flood Maps: Data, Modeling, and Local Input
- How Do You Read a FIRM? Zones, Elevations, and Floodways Explained
- Finding Your Property’s Official Flood Map
- What Flood Maps Mean for Your Insurance and Mortgage
- When Maps Change: Updates, Appeals, and LOMCs
- Why FEMA Maps Aren’t Perfect (and What to Do About It)
- Why Local Expertise Matters More Than the Map Alone
- Get Help Turning Your Flood Map Into the Right Coverage
- Frequently Asked Questions
- Sources
How FEMA Flood Maps Work: The Core Products You Need to Know
FEMA doesn’t publish just one type of map. It maintains a family of related products, and each one serves a different purpose. Confusing them is one of the most common mistakes homeowners make when they try to research their own risk.
The Flood Insurance Rate Map (FIRM) is the one that matters most. It’s the official, legally recognized map that lenders and communities use to determine flood zones, set Base Flood Elevations, and enforce building codes. If your closing attorney or mortgage company mentions a “flood determination,” they pulled it from the FIRM.
Older properties may still reference a Flood Hazard Boundary Map (FHBM), an earlier generation of flood mapping FEMA used before more detailed engineering studies were available. FHBMs identified general flood hazard areas but lacked the precision of a modern FIRM, and most communities have long since been upgraded to FIRM coverage.
The National Flood Hazard Layer (NFHL) is the digital, GIS-based version of FIRM data, and it’s what powers most of the online map viewers you’ll encounter. Behind every FIRM sits a Flood Insurance Study (FIS), a technical report containing the hydraulic and hydrologic engineering data, flood profiles, and elevation tables that justify the zones drawn on the map.
- FIRM: the regulatory map lenders and communities enforce.
- FHBM: a legacy product, mostly phased out but occasionally still referenced for older records.
- NFHL: the digital data layer behind current online map viewers.
- FIS: the engineering report explaining how the elevations and zones were calculated.
Only the FIRM and NFHL carry regulatory authority today. The FIS is supplemental but essential if you ever need to understand exactly how your Base Flood Elevation was derived.
How FEMA Creates Flood Maps: Data, Modeling, and Local Input
Flood maps aren’t drawn by guesswork or satellite imagery alone. FEMA builds them from a layered process that combines historical data with hydraulic modeling and, increasingly, direct input from the communities being mapped.
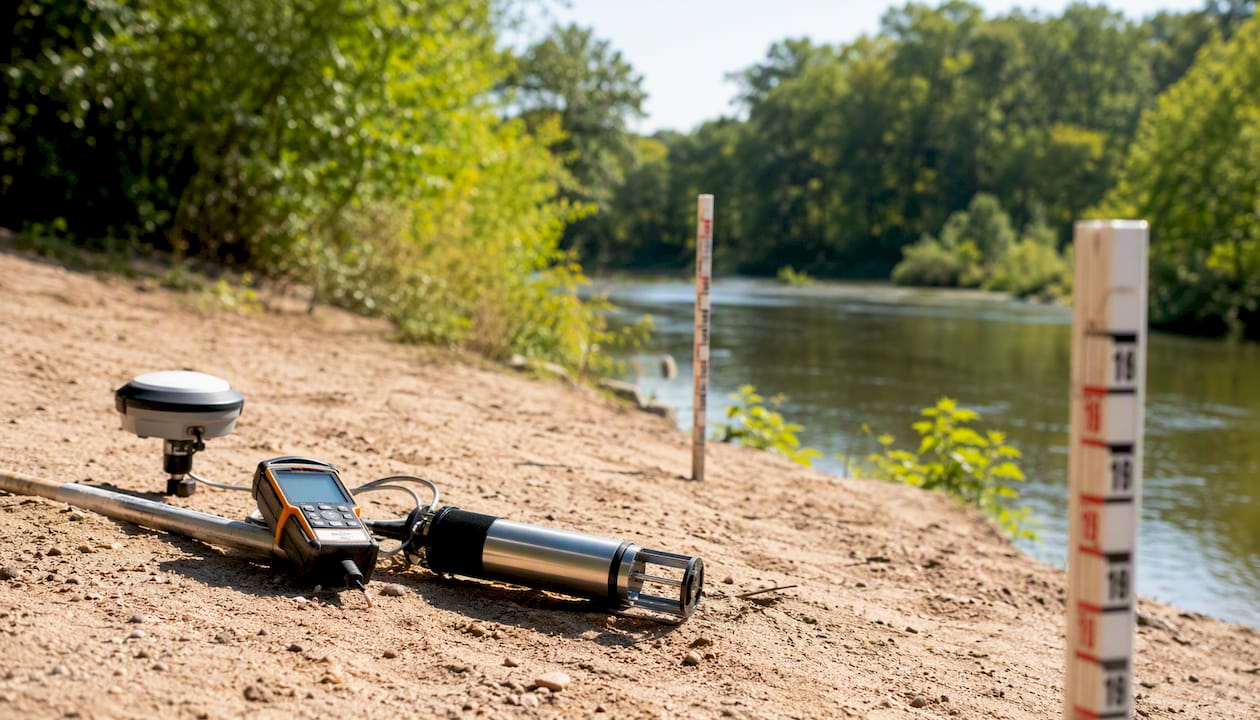
The raw inputs include decades of rainfall and storm records, river gauge data, tidal patterns along the coast, and detailed topographic surveys. Engineers also factor in levees, dams, and drainage infrastructure, since a well-maintained levee system can change how far floodwater is expected to travel, and a failing one can do the opposite. Land use and development patterns matter too. A subdivision built over what used to be absorbent farmland changes how fast water runs off during a storm.
From there, the process moves through a predictable sequence:
- Data collection — gathering historical flood events, elevation surveys, and infrastructure records for the study area.
- Hydrologic and hydraulic analysis — modeling how much water a storm of a given probability would generate and how it would move across the terrain.
- Base Flood Elevation calculation — determining the water surface elevation expected during a flood with a 1% annual chance of occurring.
- Map drafting and review — translating that data into zone boundaries and elevation lines on the FIRM.
FEMA’s Risk MAP program is where local knowledge enters the equation. Risk MAP works directly with Tribal nations, states, and individual communities to collect flood hazard data and refine the resulting maps, and it also produces non-regulatory supplements like Flood Risk Reports and Flood Risk Databases that go beyond the basic FIRM. Communities that participate actively, sharing drainage studies or updated elevation surveys, tend to end up with maps that reflect their real conditions rather than outdated assumptions from decades past.
How Do You Read a FIRM? Zones, Elevations, and Floodways Explained
This is where most homeowners get lost, and it’s also where the map actually tells you something you can act on. Every FIRM uses a system of zone codes, and each code carries a different level of risk and a different insurance obligation.
FEMA defines a Special Flood Hazard Area (SFHA) as any zone with at least a 1% annual chance of flooding, what most people call the “100-year floodplain.” That single number is more alarming than it sounds. FloodSmart notes that a 1% annual chance translates to at least a one-in-four chance of flooding over the life of a standard 30-year mortgage.
| Zone Code | Risk Level | What It Means for You |
|---|---|---|
| A, A1-A30, AE | High risk (SFHA) | Detailed study available; mandatory flood insurance if federally backed mortgage |
| V, VE | High risk, coastal | Wave action expected; mandatory insurance and stricter building standards |
| AO, AH | High risk, shallow flooding | Sheet flow or shallow ponding expected; insurance still typically required |
| X (shaded) | Moderate risk | Often the 500-year floodplain; insurance optional but frequently recommended |
| X (unshaded), B, C | Minimal risk | Outside mapped floodplain; insurance not required but not impossible |
Base Flood Elevations (BFEs) are the number that turns an abstract zone label into a concrete decision. A BFE tells you the water surface elevation expected during a base flood event, and in AE and VE zones, your home’s elevation relative to that BFE affects both your insurance premium and whether local code requires you to elevate a new structure. You’ll find BFE values printed directly on the FIRM in studied areas, with the underlying calculations documented in the FIS report.
A floodway is the channel of a river or stream, plus the adjacent land, that FEMA reserves to carry floodwater without raising the water surface elevation more than a set amount. Building in a floodway is heavily restricted because encroachment there pushes water somewhere else, usually onto a neighbor’s property.
Pro Tip: Pull up your address on the Map Service Center and generate a FIRMette before you ever talk numbers with a contractor or a lender. It’s a free, printable excerpt of your exact parcel, and it saves you from relying on a secondhand description of your zone.
Finding Your Property’s Official Flood Map
Search results and real estate sites often show flood zone estimates, but none of them replace the FEMA Flood Map Service Center, the only source with legal authority for insurance and permitting decisions.
- Go to the MSC and enter your street address, city, and state in the search box.
- Review the results carefully. The system will show you whether an effective map (currently in force) or a preliminary map (adopted but not yet enforceable) applies to your parcel. These can show different zones for the same address.
- Click through to view your panel and confirm the zone designation, any BFE values shown, and the panel’s effective date.
- Use the FIRMette tool to generate and download a printable excerpt of your specific location, which you can save for insurance applications or building permits.
- If you need the underlying engineering data, search the same address for the associated Flood Insurance Study (FIS) report, available as a downloadable PDF through the MSC portal.
Third-party map viewers and older datasets, sometimes called Q3 data, can lag behind the current effective FIRM by years. FEMA’s own flood map glossary notes that legacy products like Q3 lack the regulatory standing of a current digital FIRM or an approved Letter of Map Change. Always confirm your zone on the MSC directly rather than trusting a real estate listing’s flood disclosure.
What Flood Maps Mean for Your Insurance and Mortgage
Your flood zone isn’t just a technical classification. It’s the trigger that determines whether flood insurance is required, optional, or something you should seriously consider anyway.
If your property sits in an SFHA (any A or V zone) and you have a mortgage from a federally regulated or federally backed lender, that lender is required to mandate flood insurance as a condition of the loan, similar to how you might need to comply with boat registration rules when moving states for watercraft compliance. This isn’t a suggestion your bank makes. It’s a federal requirement tied directly to your FIRM zone. Lenders pull your flood determination at closing and can force-place a policy, usually at a much higher cost, if you let coverage lapse.
Outside the SFHA, in zones like X or the shaded 500-year floodplain, insurance typically isn’t required by a lender. But “not required” and “not needed” are two very different things. A significant portion of NFIP flood claims come from properties outside high-risk zones (https://www.floodsmart.gov/flood-zones-and-maps/what-is-my-flood-zone), because maps model probability, not certainty, and Louisiana’s rainfall patterns don’t always respect a line drawn on a panel.
A short checklist before you assume you’re covered or exempt:
- Read your lender’s flood determination letter carefully; it names your exact zone, not just “high risk” or “low risk.”
- Ask your agent whether NFIP coverage or a private flood policy fits your situation better, since pricing and coverage limits can differ significantly.
- If you’re outside the SFHA, weigh the cost of coverage against your area’s actual flood history, not just the zone label.
- Never assume your homeowners policy covers flood damage. It almost never does.
When Maps Change: Updates, Appeals, and LOMCs
Flood maps aren’t static documents. FEMA revises them regularly as new data comes in, and the update process follows a predictable, if lengthy, path from draft to enforcement.
A new or revised map starts as a preliminary map, released for public review and comment. Communities and property owners get a window to challenge the data before it’s finalized. Once that review period closes and any appeals are resolved, FEMA issues a Letter of Final Determination (LFD), and the new FIRM typically becomes effective six months later, giving communities time to adopt it into local ordinances.
| Stage | What Happens | Typical Timing |
|---|---|---|
| Preliminary map release | Draft map published for public review | Varies by project |
| Appeal period | Communities submit technical data to challenge the draft | 90 days |
| Letter of Final Determination | FEMA confirms the map is finalized | After appeals resolved |
| Effective map | New FIRM becomes legally enforceable | after LFD enforcement |
If you believe your individual property is mismapped, you don’t have to wait for a community-wide revision. FEMA offers three main Letter of Map Change (LOMC) products:
- A Letter of Map Amendment (LOMA) corrects the map based on existing conditions, often used when a structure sits on natural high ground above the BFE.
- A Letter of Map Revision (LOMR) reflects a physical change, like a new levee or drainage project, that alters the flood hazard.
- A LOMR-F removes a specific structure from the SFHA after fill has been added to raise it above the BFE.
An elevation certificate prepared by a licensed surveyor is usually the single most persuasive piece of evidence in a successful LOMA or LOMR-F application. If you’re considering an appeal on behalf of your property, our guide to the FEMA flood map appeal process walks through what documentation to gather before you file.
Why FEMA Maps Aren’t Perfect (and What to Do About It)
Flood maps are a snapshot of conditions at the time they were studied, not a live forecast. That gap matters more than most homeowners realize.
Development changes drainage patterns faster than maps get updated. A parking lot or subdivision built upstream from your property increases runoff and can raise flood risk in ways the current FIRM doesn’t yet reflect. Coastal erosion reshapes shorelines. Rainfall intensity in many regions has shifted from the historical averages that older studies relied on. FEMA itself treats flood risk as dynamic, which is exactly why Risk MAP exists as an ongoing program rather than a one-time mapping exercise.
The rule people usually mean when they invoke that phrase relates to the cost of improvements or repairs relative to a structure’s value under local floodplain ordinances, not to map accuracy itself. Don’t let a secondhand rumor substitute for reading your actual FIRM and FIS.
The bigger misconception is treating “outside the SFHA” as “no risk.” It means lower statistical probability, not zero probability, and Louisiana’s flood history is full of properties that learned that distinction the expensive way.
- If your zone designation seems wrong for your actual elevation, order a professional elevation certificate before assuming the map is outdated.
- Pull the FIS report for your area to understand the engineering assumptions behind your BFE.
- Talk to your local floodplain administrator, who often has more current data than what’s reflected on the published FIRM.
- If the evidence supports it, file for a LOMA or LOMR-F rather than just hoping the next map update fixes it.
Pro Tip: Keep a folder with your elevation certificate, FIRMette, and FIS excerpt together. When you refinance, sell, or file a claim, having this on hand saves days of back-and-forth with underwriters.
Why Local Expertise Matters More Than the Map Alone
A flood map tells you a probability. It doesn’t tell you what to do about it, and that’s where I’ve watched too many well-meaning homeowners go wrong.
I’ve spent more than 20 years helping Louisiana families and business owners translate flood zone data into actual coverage decisions, and the pattern is consistent: the people who come out ahead after a storm are the ones who treated the FIRM as a starting point, not a final verdict. A zone code doesn’t account for the drainage ditch behind your neighbor’s fence that hasn’t been cleared in a decade, or the fact that your parish updated its levee system two years after your map was last revised. Those details live in local knowledge, not in a federal database.
This is also why a responsive agent matters when something goes wrong. When a LOMR-F application needs an elevation certificate, or a claim adjuster questions whether your zone designation affected your payout, you need someone who has actually read the FIS report for your parish, not someone reading from a script. Our catastrophe response team deploys directly to disaster zones after major storms, because paperwork moves faster when someone local is standing in front of you instead of on hold with a call center three states away.
Treat the map as one input among several. Then sit down with someone who can turn that input into a coverage decision that actually protects what you’ve built.
Get Help Turning Your Flood Map Into the Right Coverage
Reading a FIRM correctly is only half the job. The other half is knowing what coverage actually protects you once you understand your real exposure, and that’s where a local agent who’s seen Louisiana flood claims up close makes the difference between a policy that pays and one that leaves you arguing with an adjuster.
The Root Agency has spent more than 20 years helping families across Louisiana and Mississippi interpret their flood zones, review Base Flood Elevations, and choose coverage that matches their real risk, not just the minimum a lender requires. Steve Root built this agency on the belief that insurance only works if someone answers the phone when you need them, and our 356 five-star Google reviews reflect two decades of doing exactly that. When storms hit, our mobile catastrophe response unit deploys directly to affected communities, because claims move faster with a local presence than with a call center. Whether you need help reading your FIRMette, gathering documentation for a LOMR-F application, or simply reviewing whether your current flood policy actually covers your rebuild cost, visit our flood insurance page or call (225) 926-0160 to schedule a policy review today.
Frequently Asked Questions
What is the difference between a FIRM and an NFHL? A FIRM is the official paper or PDF map product for a specific jurisdiction. The NFHL is the digital, GIS-based database containing the same regulatory flood zone data, which powers most online map viewers.
Do I have to buy flood insurance if I’m not in a high-risk zone? Not by law, but many homeowners choose to anyway. Zones outside the Special Flood Hazard Area still see a meaningful share of NFIP claims, since maps reflect probability rather than a guarantee.
How long does it take to get a Letter of Map Amendment? Processing times vary based on FEMA’s workload and how complete your application is, but a professional elevation certificate submitted with strong technical data typically moves faster than an incomplete request.
Can my flood zone change without notice? No. Map updates go through a preliminary release, a public and community appeal window of 90 days, and a Letter of Final Determination before becoming effective, giving property owners advance notice throughout the process.
Is a FEMA flood map the same as my insurance premium? No. The map determines your zone and whether coverage is required, but your actual premium depends on additional factors like your building’s elevation relative to the BFE, construction type, and coverage limits you choose with your agent.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
A handful of official tools cover almost everything a property owner needs to verify their own flood risk without guessing.
Bookmark the MSC specifically. Download a copy of your effective FIRM or FIRMette for your records now, before you need it for a refinance, a permit application, or a claim.